CMHC Refinance is insured financing for an owner adding a self-contained secondary suite to a home in Canada. It is a mortgage product, not a grant, and CMHC insurance terms do not promise that a lender will approve a particular borrower or project.
Check the occupancy and project purpose
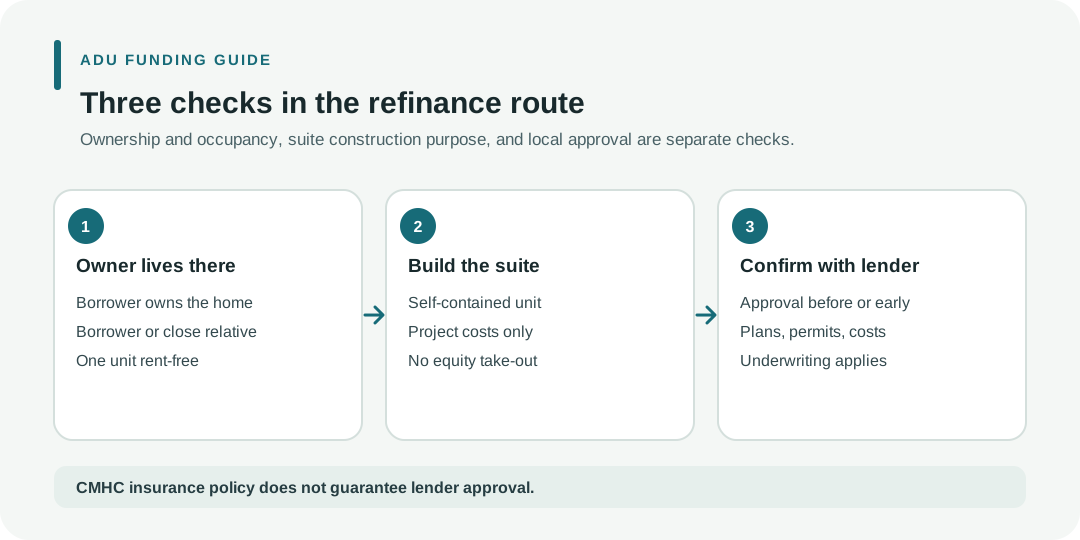
The borrower must already own the home, and the borrower or a close relative must live there. At least one unit must be occupied rent-free by the borrower or a qualifying relative. The new suite must comply with local bylaws and regulations. CMHC excludes short-term rental use under this product when stays are shorter than 90 consecutive days.
Financing is limited to construction and completion costs for the suite; it cannot fund unrelated equity take-out. CMHC approval must occur before construction or at an early stage. Ask the lender what counts as early enough for the selected file.
Know the published policy limits
For an owner-occupied home with no more than four total units, CMHC lists a maximum loan-to-value ratio of 90%. The maximum lending or as-improved value must be below C$2 million, and the maximum amortization is 30 years. These limits sit alongside lender debt-service, credit, valuation, and underwriting requirements; they do not calculate a personal approval amount.
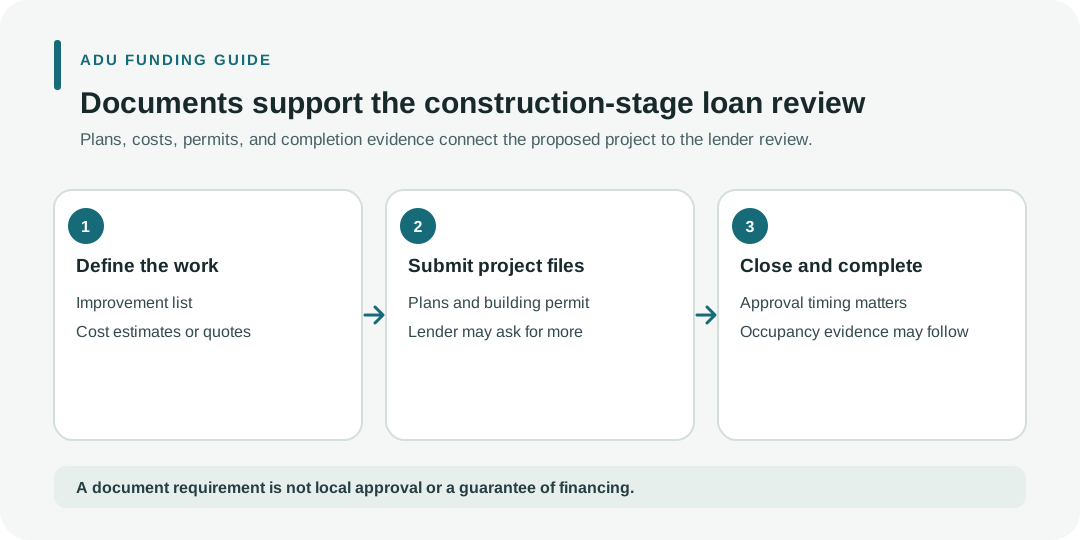
CMHC lists project documents such as improvement details and cost estimates, building plans, a building permit, and an occupancy permit or qualified-professional report confirming compliance. A lender can require additional documents. Local permission, building-code compliance, utility capacity, and permission to occupy remain separate decisions by local authorities.
Keep it separate from the announced federal loan
The 2025 federal budget lists the proposed Canada Secondary Suite Loan Program in its planned-reductions material. That separate initiative should not be treated as an active homeowner loan or combined with CMHC Refinance. Verify current product and lender availability before committing to a construction budget.
For other public-program types and status checks, see the ADU grants and programs guide. The public mortgage and appraisal policy guide compares lender rules without deciding whether a suite is permitted at a specific address.
Key points
- CMHC Refinance is insured mortgage financing for suite construction and completion, not a grant.
- Ownership, occupancy, short-term-rental, project-cost, timing, and local-compliance rules matter.
- LTV, value, and amortization limits do not establish an approved amount or local eligibility.
- Confirm current terms with CMHC and a participating lender before work begins.