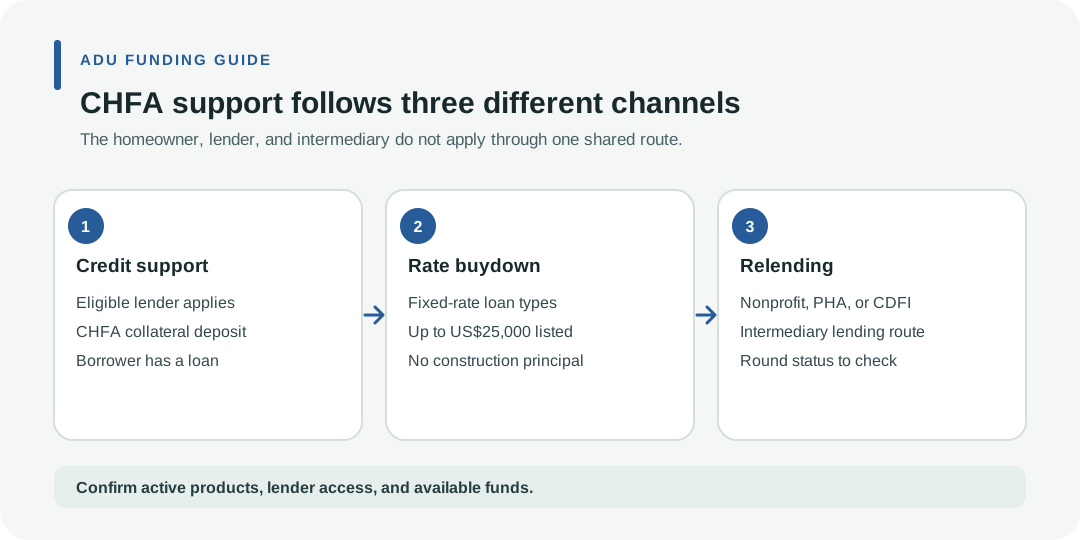
Colorado Housing and Finance Authority (CHFA) lists several ADU finance programs, but they support different transactions and applicants. Credit enhancement and an interest-rate buydown run through eligible lenders. Relending supports intermediary organizations. They are not three grants a homeowner can combine.
Credit enhancement: lender collateral, not a homeowner award
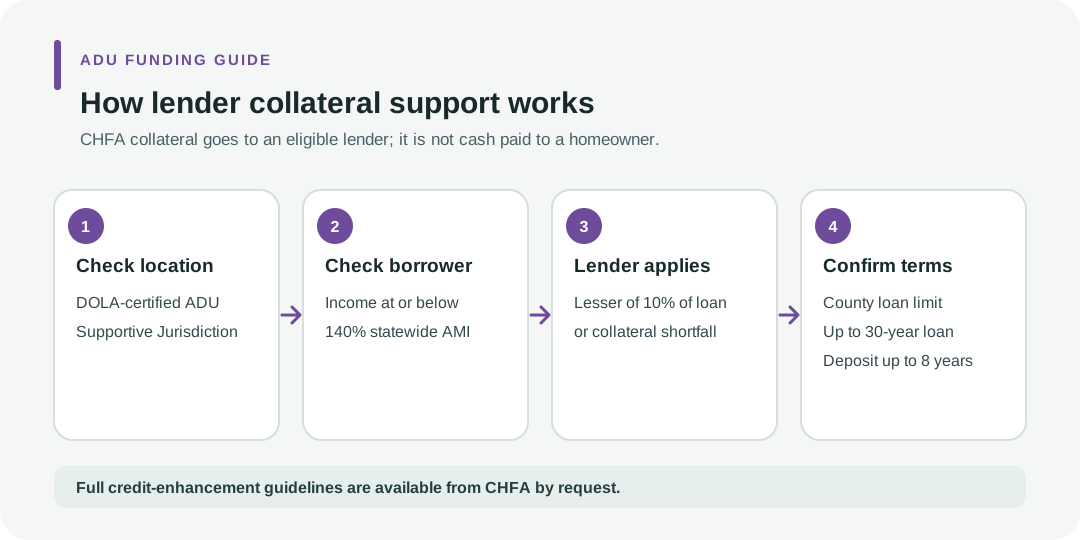
CHFA’s Credit Enhancement Program supports eligible lenders making qualifying ADU loans in a DOLA-certified ADU Supportive Jurisdiction. The borrower must meet CHFA’s published income test of no more than 140% of statewide area median income. CHFA deposits cash collateral with the lender, up to the lesser of 10% of the eligible loan or the lender’s demonstrated collateral shortfall. That deposit can help reduce required equity or support a larger loan, but it is not cash paid to the homeowner.
The public summary refers to the county conventional loan limit, caps maturity and amortization at 30 years, and limits the deposit to eight years or the shorter loan term. Lenders apply to CHFA. Funding is first-come until depleted, but the page does not publish a remaining balance; ask CHFA for the full guidelines and current lender route.
Interest-rate buydown: a different eligible loan
CHFA lists a permanent interest-rate buydown of up to US$25,000 for eligible fixed-rate home-equity loans or cash-out first mortgages. The public rules exclude HELOCs and temporary buydowns. This support reduces the interest rate on a qualifying transaction; it does not pay the ADU’s construction principal. A homeowner still needs a participating lender and must meet the income and supportive-jurisdiction tests. Ask whether a lender is currently participating and whether funds remain before structuring the financing.
Relending: an intermediary funding channel
The ADU Relending Program directs resources to eligible nonprofit organizations, public housing authorities, and community development financial institutions. It is not an individual homeowner application. CHFA’s published competitive-round timing elapsed in January 2026; the page does not establish current intermediary capacity or a later round. Contact CHFA and the relevant local intermediary for present availability.
Do not confuse CHFA with the state grant round
Colorado DOLA’s July 2026 newsletter described a separate ADU grant round for local governments, with a published application window of August 3 through August 31, 2026. That window has elapsed. The notice does not establish an award to a particular municipality or homeowner assistance; it is not a CHFA lender program.
For any route, verify supportive-jurisdiction status, current program documents, income measure, lender or intermediary, funding, loan terms, and local ADU approval. The program comparison guide explains why an announcement or maximum does not prove an open application.
Key points
- A lender applies for credit enhancement; the collateral deposit is not a homeowner grant.
- The buydown covers eligible loan types and does not fund construction principal.
- Relending serves intermediaries, while DOLA’s elapsed round served local governments.
- Confirm current intake, lender access, county limits, and funds with CHFA.